


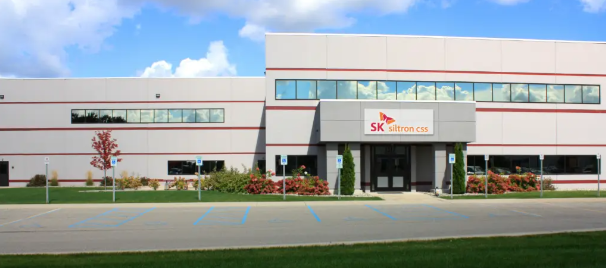
South Korea’s sole silicon wafer producer SK Siltron has begun liquidation of its U.S. subsidiary SK Siltron CSS in Michigan, with full closure targeted by end-2026. The Bay County SiC fab will phase out production of silicon carbide substrates for EV power chips, with most employees set to leave.

The shutdown follows an asset restructuring negotiation with Doosan Group. SK Siltron acquired DuPont’s SiC business for $450 million** in 2019 but is exiting after just seven years, driven by **EV market slowdown**, **global overcapacity** in SiC substrates, price compression, and persistent losses – which contributed to **SK Siltron’s 2025 consolidated net loss of KRW 293.6 billion ($190 million).
Doosan’s acquisition interest is limited to the profitable silicon wafer business, so the SiC line must be closed first. Post-exit, SK Siltron is doubling down on silicon wafers – its new Gumi Plant 4 (KRW 2.3 trillion) is now operational, boosting 300mm wafer capacity by 50%, with AI chip demand driving strong order growth.
Group-level, SK is reallocating resources toward high-margin memory. SK Group Chairman Chey Tae-won recently forecast global semiconductor demand growth of 50-60% in 2027, with AI-related chips up 60-100% , and limited new supply next year set to widen the gap.
From ICgoodFind: SK Siltron just cut its losses on SiC to double down on 300mm silicon. When a major player exits a market, overcapacity is real – the signal is loud and clear.







